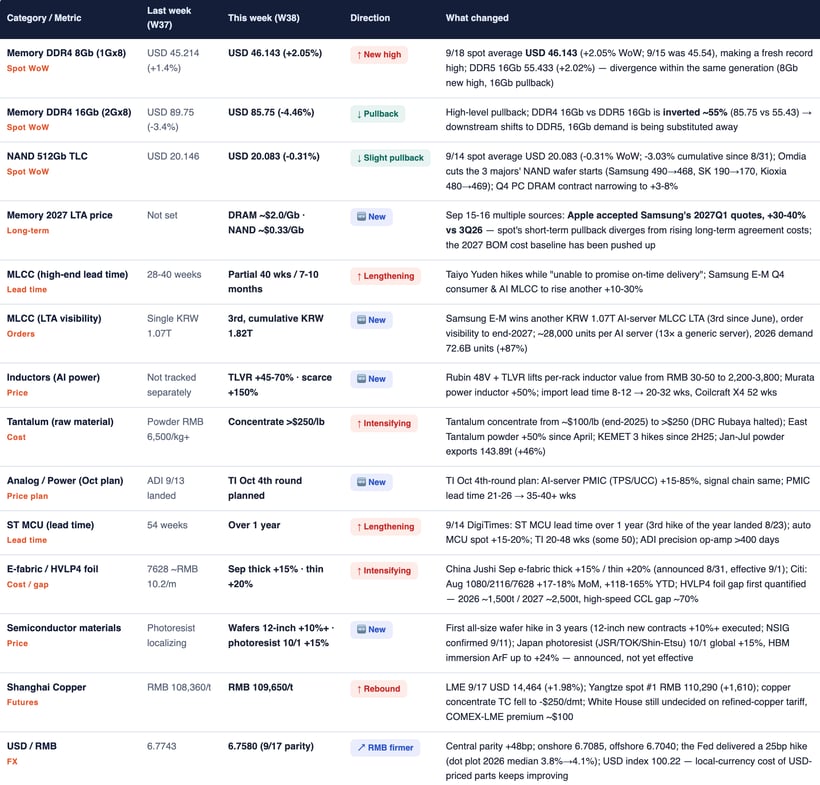
1. Week-over-Week Comparison — Segment Changes & Drivers
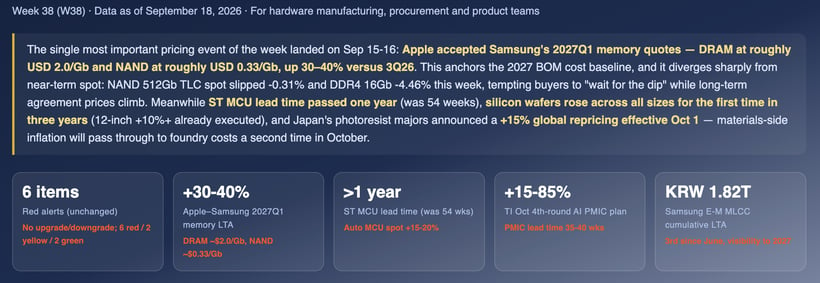
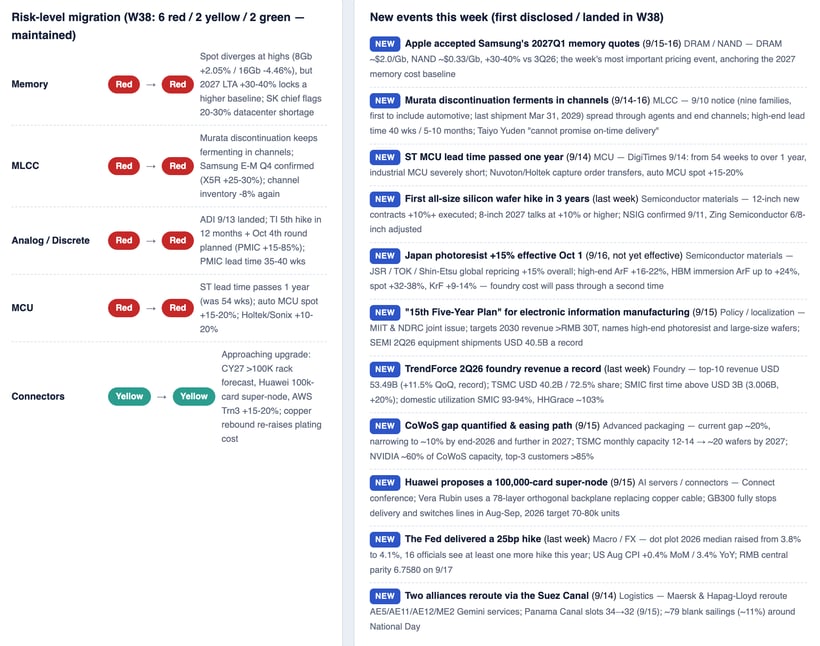
Comparison window: W37 (2026.09.04–09.11) vs W38 (2026.09.11–09.18). Fourteen categories / metrics moved materially this week; no risk-level upgrade or downgrade (rating holds at 6 red / 2 yellow / 2 green), but three structural shifts are resetting the 2027 cost baseline — memory long-term agreement pricing, MCU lead-time lengthening, and semiconductor-materials inflation.
2. Five Forces Driving the Market This Week
- 2027 LTA pricing power
Apple accepted Samsung's 2027Q1 memory quotes (+30-40%); Samsung E-M MLCC LTA cumulative KRW 1.82T to end-2027 — head customers lock 2027 capacity, generic parts shrink, mid/small buyers face higher premiums. - Mature-node supply squeeze
ST MCU lead time >1 year; TI PMIC lead time 35-40+ wks with an Oct 4th-round +15-85% plan; 8-inch effective capacity -2.4% in 2026 — MCU / analog / power scheduling stays constrained into 2027. - Materials-side full-chain hike
Wafers rise across all sizes (+10%+); Japan photoresist +15% (Oct 1); China Jushi e-fabric thick +15% / thin +20%; HVLP4 foil gap quantified — foundry and CCL costs pass through a second time in October. - AI super-node architecture
Huawei 100k-card super-node; Vera Rubin 78-layer orthogonal backplane replaces copper cable; CY27 >100K rack forecast — per-rack value lifts (MLCC 28k units, inductor RMB 2,200-3,800, connectors $500-2,000). - Macro & logistics shift
Fed delivered a 25bp hike (dot plot 2026 median 4.1%); copper rebounds (LME +1.98%); two alliances reroute via Suez, Panama slots cut — a mixed cost picture for plating, freight and FX.
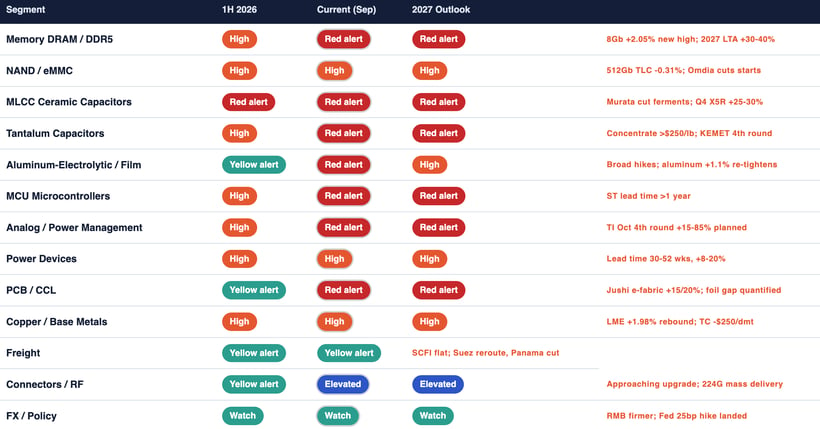
3. Risk Heat Map — 13 Segments × Three Time Windows
Color block = supply / price tightness. Bold outline = moved this week. Red = rising / high risk, green = falling / loose supply-demand (China market convention).
4. Memory — Spot Diverges at Highs, But 2027 LTA Locks a Higher Cost Baseline
DDR4 8Gb spot makes a new high of USD 46.143 (+2.05%) while DDR4 16Gb pulls back -4.46% and NAND 512Gb TLC slips -0.31% — spot moved to "diverging at highs." Meanwhile Apple accepted Samsung's 2027Q1 quotes at +30-40% vs 3Q26, so the 2027 long-term cost baseline has already been lifted even as near-term spot cools.
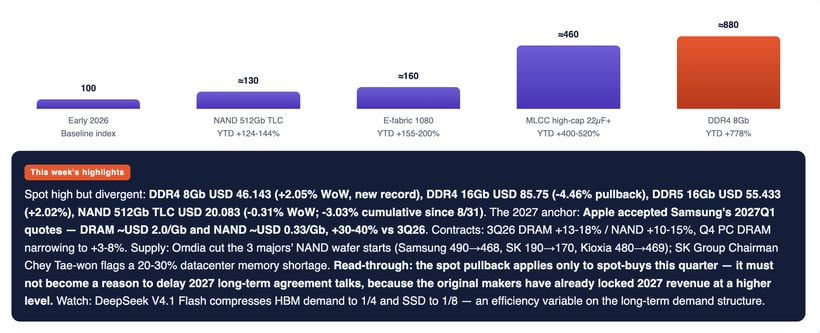
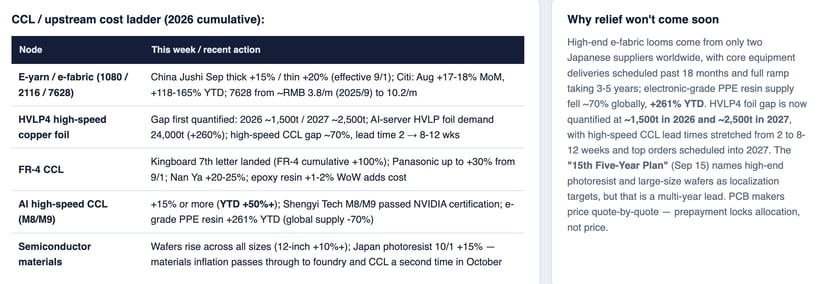
5. PCB & CCL — E-Fabric Rises Again, HVLP4 Foil Gap Quantified for the First Time
The shortage keeps moving upstream along "yarn → fabric → CCL", and the materials-side is now inflating for a second time — wafers and photoresist join e-fabric and copper foil.
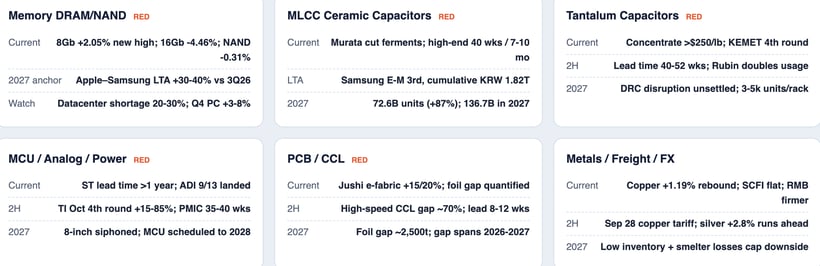
6. Segment Snapshot
7. This Week's Procurement Playbook — What to Do Now
Standing section, rewritten each week for the changes. Pull-in strategy runs parallel to cost-down / substitution paths.
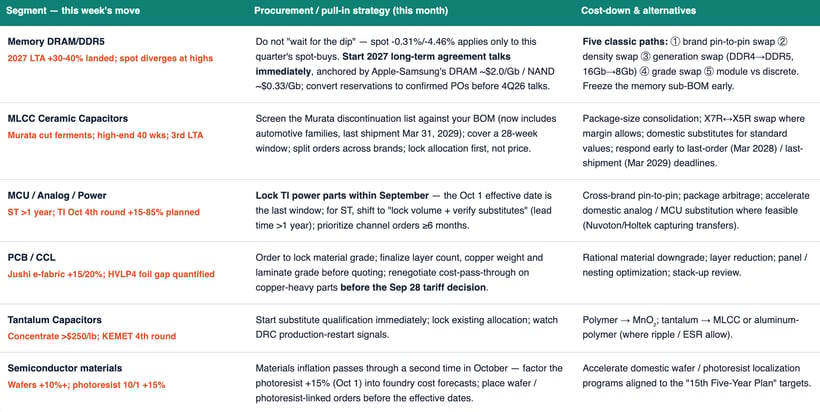
Substitutes typically need a 6-12 week qualification cycle. Our market-intelligence team maintains a cross-category pre-qualified substitute list — the qualification clock is already running, see §11.
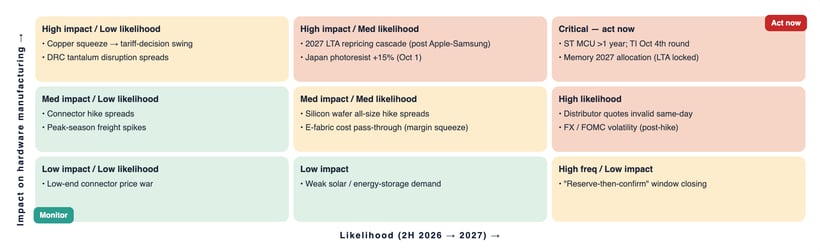
8. Risk Matrix — Likelihood × Impact
Attention allocation: act immediately in the top-right, monitor continuously in the bottom-left.
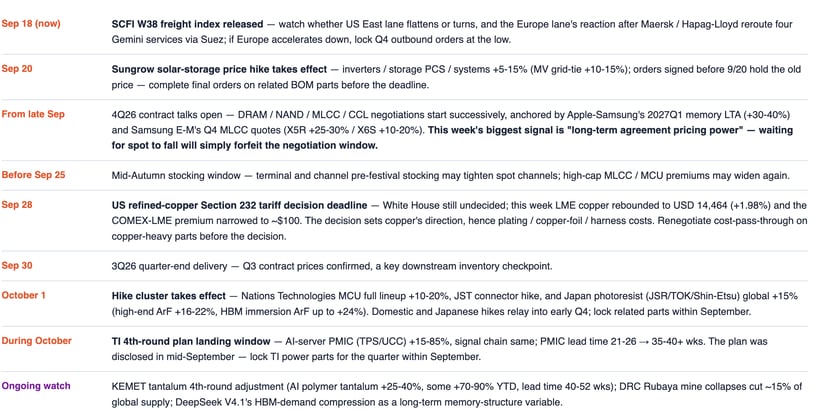
9. Decision Timeline — Near-Term Windows & Key Nodes
10. Two Scenarios into 2027
Base case — orderly escalation
- 2027 memory LTA repricing (post Apple-Samsung) cascades into 4Q26 contract talks; memory, MLCC and CCL pass through in steps per announced cadence into 1H27.
- Copper stabilizes after the Sep 28 tariff decision; photoresist +15% and wafer hikes pass through once in October, then settle into a new cost base.
- Those who locked orders early or indexed gain cost visibility; unhedged BOMs revalue quarter by quarter.
Stress case — compounding shortages
- Murata's generic-line discontinuation triggers follow-on exits; mid/low-end MLCC is crowded out and moves into allocation.
- Materials inflation compounds: e-fabric + foil gap + photoresist + wafers all pass through in Q4, forcing a second round of CCL and foundry price hikes.
- Under 8-inch siphoning and ST's >1-year lead time, mature-node (MCU / analog / power) stays hard to relieve before 2028.
What smart buyers are doing right now
- Do not "wait for the dip" — spot -0.31%/-4.46% applies only to this quarter's spot-buys; start 2027 long-term agreement talks now, anchored by Apple-Samsung's +30-40%.
- Screen the Murata discontinuation list against your BOM now — it now includes automotive families; last order Mar 2028 / last shipment Mar 2029, but qualification takes months.
- Lock TI power parts within September — the Oct 1 effective date is the last window before the +15-85% AI PMIC plan lands.
- Renegotiate copper cost-pass-through on connectors / harnesses / copper foil before Sep 28.
- Set all new quotes to ≤7-day validity + index-linked terms, to prevent "confirm-then-void."
- Treat allocation (not price) as the 2027 DRAM planning variable — the LTA has already locked the baseline.
Get ahead of the next step-change
Book a supply-chain acceleration review and we'll map your exposed BOM lines against this week's moves — and put pre-qualified alternates and buy-ahead options on the table.