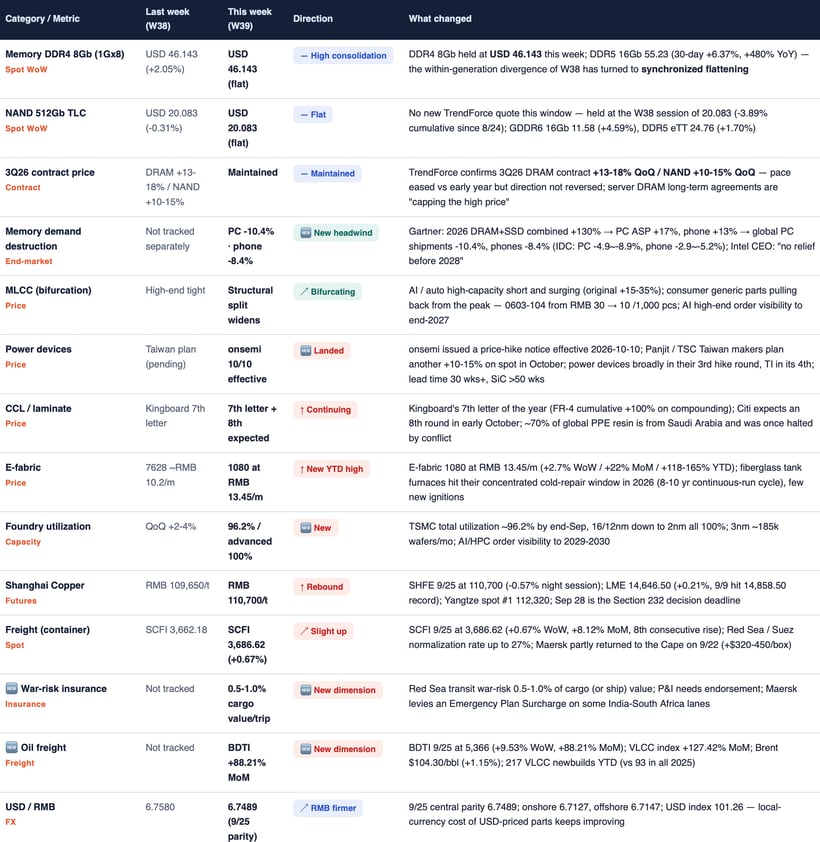
1. Week-over-Week Comparison — Segment Changes & Drivers
Comparison window: W38 (2026.09.11–09.18) vs W39 (2026.09.18–09.25). Fourteen categories / metrics moved materially; no risk-level upgrade or downgrade (rating holds at 6 red / 2 yellow / 2 green), but a new geopolitics & war-logistics dimension is now explicitly tracked, alongside memory demand destruction and the October hike cluster.
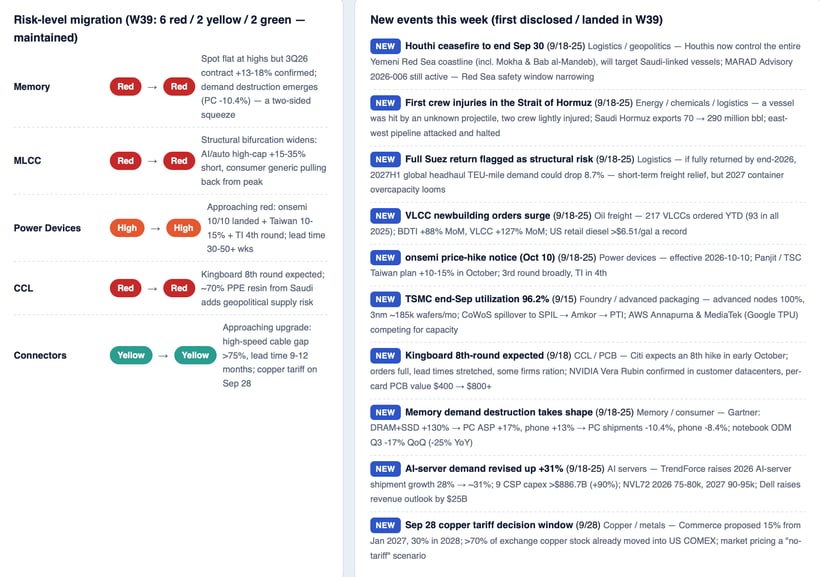
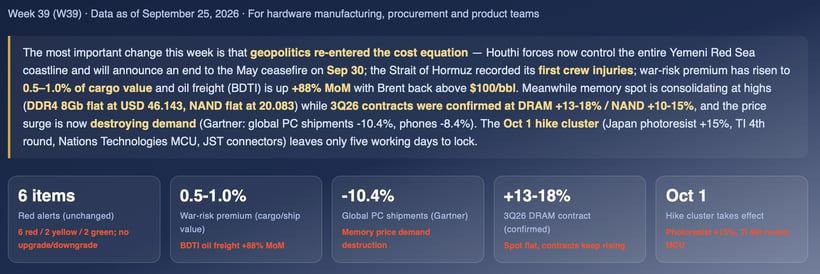
2. Five Forces Driving the Market This Week
- Geopolitics re-enters cost
Houthi ceasefire ends Sep 30; Hormuz first crew injuries; war-risk 0.5-1.0%, BDTI +88% MoM, Brent >$100 — energy & chemical raw materials, freight and insurance all reprice. - Memory demand destruction
DRAM+SSD +130% pushes PC ASP +17% / phone +13%, cutting PC shipments -10.4% and phones -8.4% — price hikes now feed back into end-demand shrinkage. - October hike cluster
Photoresist +15% (Oct 1), TI 4th round (AI PMIC +15-85%), Nations Technologies MCU +10-20%, JST connectors, COSCO GRI +$200/FEU, onsemi (Oct 10) — five working days to lock. - Mature-node full utilization
TSMC 96.2% / advanced 100%; SMIC 93-94%, HHGrace ~103%, mature nodes >95% with 2H26 quotes +5-15% — foundry has no room to absorb materials cost, so it passes through. - LTA pricing power
3Q26 DRAM contract +13-18% confirmed; server DRAM long-term agreements "capping the high"; 2027 capacity locked by head customers — spot consolidates, contracts keep rising.
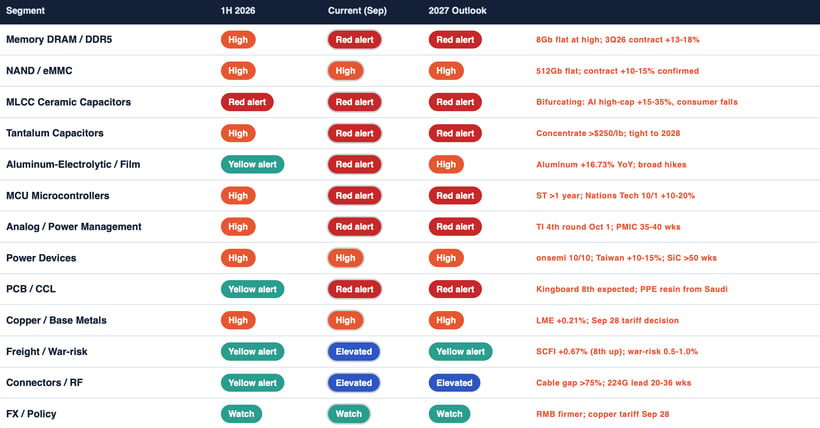
3. Risk Heat Map — 13 Segments × Three Time Windows
Color block = supply / price tightness. Bold outline = moved this week. Red = rising / high risk, green = falling / loose supply-demand (China market convention).
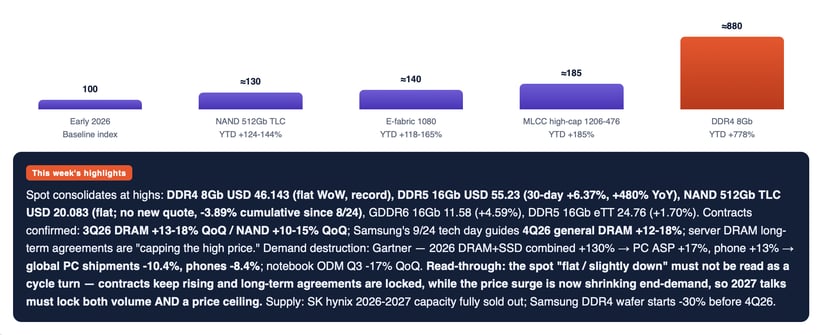
4. Memory — Spot Consolidates at Highs, Contracts Confirmed Rising, Demand Destruction Emerges
DDR4 8Gb holds at a record USD 46.143 and NAND 512Gb TLC holds at 20.083 (no new quote), while 3Q26 contracts were confirmed at DRAM +13-18% / NAND +10-15%. The new variable this week is demand destruction: Gartner estimates the +130% memory surge will push PC ASP +17% and phone +13%, cutting PC shipments -10.4% and phones -8.4%.
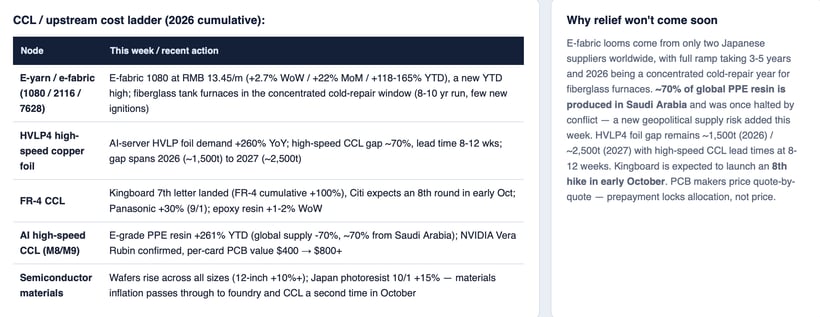
5. PCB & CCL — E-Fabric Hits New Highs, Geopolitics Reaches Into the Resin Supply
The shortage keeps moving upstream, and this week geopolitics reached directly into the supply: ~70% of global PPE resin comes from Saudi Arabia, a key material for high-speed CCL (M6+), now under conflict risk.
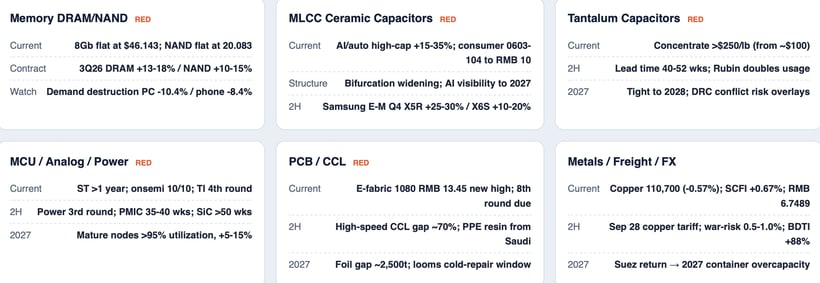
6. Segment Snapshot
7. This Week's Procurement Playbook — What to Do Now
Standing section, rewritten each week for the changes. Pull-in strategy runs parallel to cost-down / substitution paths.
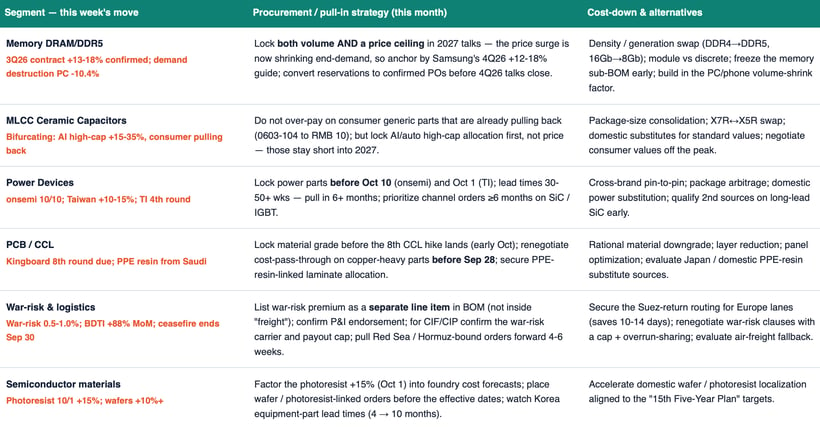
Substitutes typically need a 6-12 week qualification cycle. Our market-intelligence team maintains a cross-category pre-qualified substitute list — the qualification clock is already running, see §11.
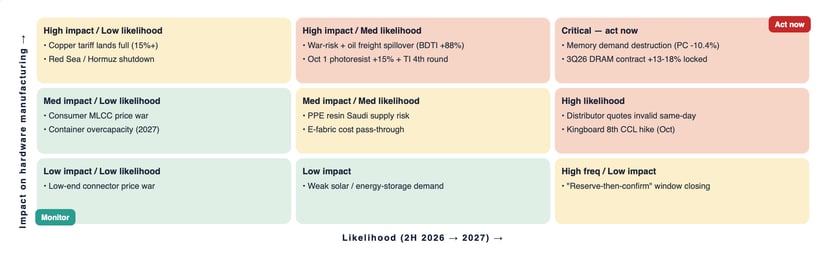
8. Risk Matrix — Likelihood × Impact
Attention allocation: act immediately in the top-right, monitor continuously in the bottom-left.
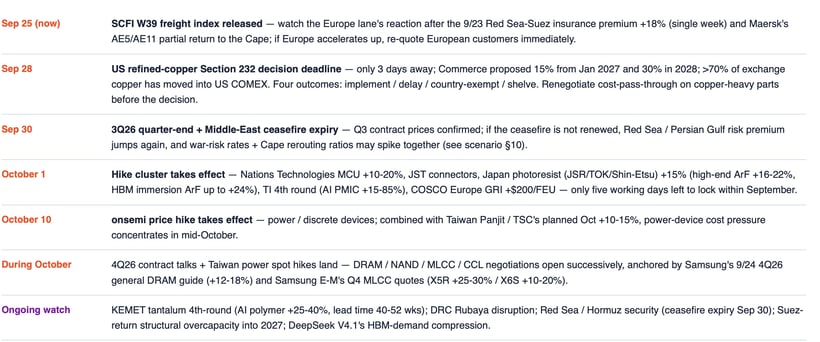
9. Decision Timeline — Near-Term Windows & Key Nodes
10. Two Scenarios into 2027
Base case — orderly escalation
- Copper tariff is delayed or country-exempt on Sep 28; copper consolidates; Red Sea / Suez normalization continues toward 50% by 4Q26, easing Europe-lane freight and war-risk.
- The Oct 1 hike cluster (photoresist +15%, TI 4th round, MCU) passes through once in October, then settles; memory contracts rise on the confirmed +13-18% cadence but spot stays "flat at highs."
- Buyers who locked early gain cost visibility; demand destruction keeps the consumer side soft, creating selective renegotiation windows.
Stress case — geopolitics + shortages compound
- Ceasefire ends Sep 30 and Hormuz attacks become frequent (first crew injuries already recorded); war-risk jumps above 1.5%, oil freight (BDTI/VLCC) keeps spiking, and several carriers return fully to the Cape.
- Saudi PPE resin is disrupted again + energy/chemical costs (ethylene oxide, titanium dioxide, PX) keep rising, forcing a second round of CCL and packaging-material hikes.
- Copper tariff lands at 15% on top, squeezing non-US deliverable supply; mature nodes stay >95% utilized, so materials costs pass through fully into Q4 and 2027.
What smart buyers are doing right now
- Lock both volume AND a price ceiling in 2027 memory talks — 3Q26 contract +13-18% is confirmed and demand destruction (PC -10.4%) gives you a lever to cap the top.
- Close power-device orders before Oct 10 (onsemi) and Oct 1 (TI) — lead times are 30-50+ weeks.
- List war-risk premium (0.5-1.0%) as a separate BOM line, confirm P&I endorsement, and pull Red Sea / Hormuz-bound orders forward 4-6 weeks before the Sep 30 ceasefire expiry.
- Renegotiate copper cost-pass-through before Sep 28; consider copper substitution on non-critical parts.
- Do not over-pay consumer MLCC that is already pulling back — but lock AI/auto high-cap allocation first, not price.
- Secure Suez-return routing for Europe lanes (saves 10-14 days) and renegotiate war-risk clauses with a cap + overrun-sharing.
Get ahead of the next step-change
Book a supply-chain acceleration review and we'll map your exposed BOM lines against this week's moves — and put pre-qualified alternates and buy-ahead options on the table.